Financial literacy is about more than managing money today.
It also means understanding how saving, investing, risk, and long-term planning can shape future financial choices. That broader view is reflected in the 2026 update to the U.S. National Strategy for Financial Literacy, released by the Financial Literacy and Education Commission (FLEC). The strategy identifies four national priority areas: Youth Financial Capability, Saving and Investing, Digital Financial Literacy, and Scams and Fraud Education.
Each priority responds to a different part of modern financial life. Young people need opportunities to build financial capability; consumers need to navigate digital financial tools responsibly; and people of all ages need to recognize scams and fraud. The explicit focus on saving and investing also reinforces a central point: financial education should prepare people to understand both everyday money management and longer-term financial decisions.
That does not mean pushing learners into real-money investing before they are ready. The educational goal is to help them understand concepts, trade-offs, risks, and behaviors before real financial consequences arrive.
What the 2026 National Strategy for Financial Literacy Says
The Financial Literacy and Education Commission brings together federal agencies to coordinate efforts that support financial literacy in the United States. Its 2026 strategy identifies four priority areas:
- Youth Financial Capability
- Saving and Investing
- Digital Financial Literacy
- Scams and Fraud Education
Together, these priorities reflect the range of situations in which people make financial decisions. Financial capability begins early, financial products and information increasingly appear in digital environments, and consumers need the knowledge to recognize misleading or fraudulent activity. Saving and investing are an important part of this picture because they connect present-day choices with future goals.
The strategy also highlights approaches to effective financial education, including timely learning, relevance to different life stages, reinforcement over time, hands-on experiences, quality instruction, and evaluation. These principles point toward a model in which financial education is not limited to presenting information; it also helps learners understand and apply it.
Why Financial Literacy Must Go Beyond Budgeting
Budgeting, banking, credit, debt management, taxes, insurance, and consumer protection remain essential foundations. They help people manage income, meet obligations, plan spending, and respond to unexpected expenses. But financial literacy cannot stop at short-term money management.
Saving and investing introduce questions about time, uncertainty, and future needs. Saving can help build a financial cushion or support a specific goal. Investing involves evaluating potential returns alongside risks, costs, and the possibility of losses. Long-term planning asks how today’s decisions may affect future options.
These topics are connected. A budget influences how much a person may be able to save. Savings can provide flexibility when circumstances change. Investment decisions introduce different forms of risk and require an understanding of time horizon and personal goals. Looking at each topic in isolation can obscure how financial choices interact.
Modern financial education should therefore connect immediate decisions with longer-term outcomes. The aim is not to make every learner a financial professional. It is to help people ask informed questions, recognize trade-offs, and understand the consequences that may follow from different choices.
What Should Saving and Investing Education Teach?
Saving and investing can be introduced through definitions, but meaningful understanding takes context and practice. Learners need to understand key concepts and how those concepts affect decisions.
- Compound growth and inflation: Compounding describes how returns or interest can build on earlier growth over time. Inflation affects what money can buy, which is why the value of money over time matters when planning for future goals.
- Risk and return: Potential returns should be considered alongside uncertainty and the possibility of loss. Higher potential returns do not come without trade-offs, and no outcome is guaranteed.
- Diversification and volatility: Diversification means spreading exposure rather than concentrating everything in one place. Volatility describes how prices change over time; understanding it can help learners interpret market movement without assuming every change signals a lasting trend.
- Liquidity and opportunity cost: Liquidity concerns how readily an asset can be converted into cash. Opportunity cost is what someone gives up when choosing one option over another. Both concepts can affect financial decisions.
- Time horizons and goals: A financial decision should be understood in relation to when money may be needed and what it is intended to support. Different goals and time horizons can involve different considerations.
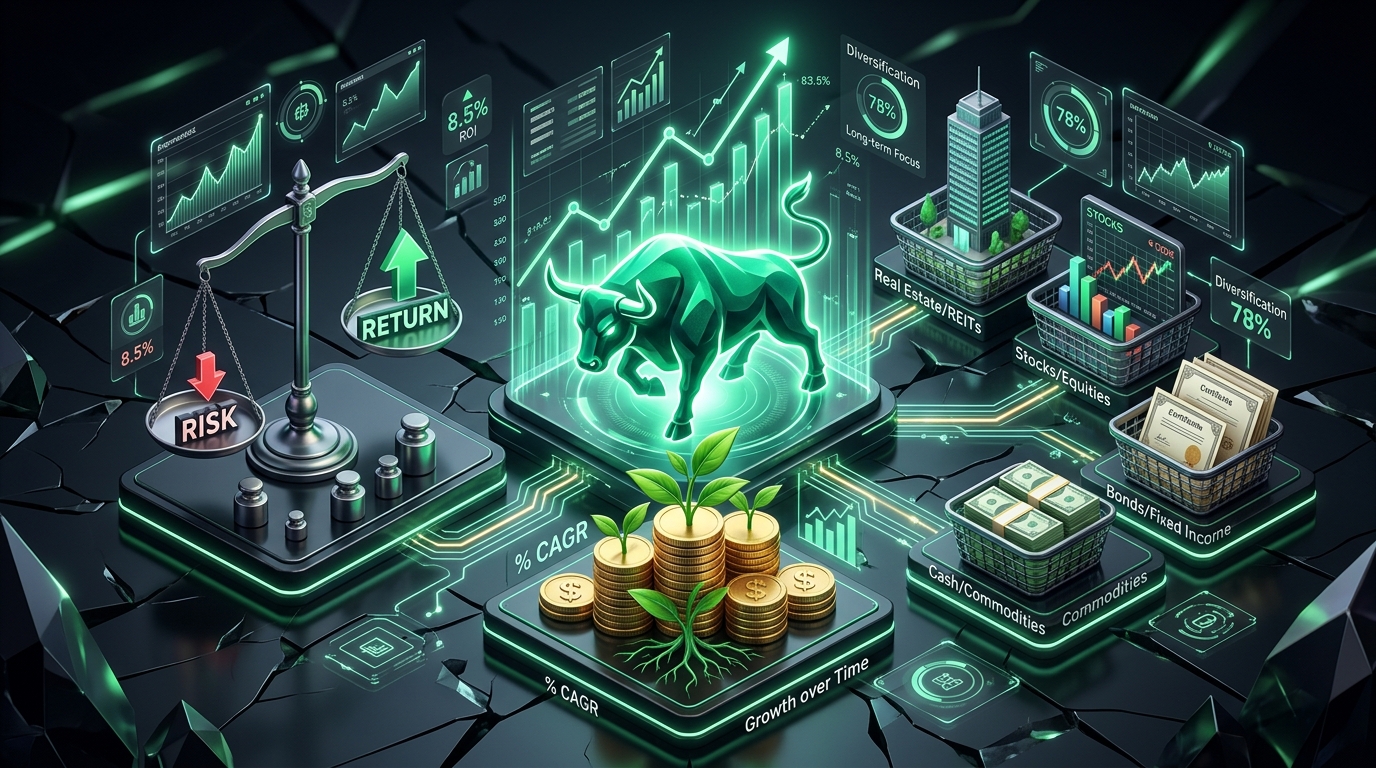
The goal is to move beyond memorizing terminology. A learner may be able to define diversification without understanding how concentration changes exposure to risk. Someone may know that markets rise and fall without understanding how volatility can affect decisions. Practical examples help connect these concepts to real situations.
Why Practical Financial Education Matters
Knowing a concept and applying it are different skills. A learner may understand the definition of a savings goal but still need practice comparing priorities, planning contributions, and adjusting when circumstances change. Likewise, understanding market vocabulary does not automatically prepare someone to interpret new information or think carefully about risk.
Practical financial education creates opportunities to revisit concepts, make choices, receive feedback, and reflect on outcomes. Repetition can reinforce learning, while realistic scenarios help learners see how multiple considerations interact. Assessment can also help educators identify what learners understand and where additional support may be useful.
The process should make room for mistakes. In a well-designed learning environment, a poor choice can become an opportunity to examine assumptions and try a different approach. The objective is not to eliminate uncertainty from financial life; it is to help learners develop the judgment to respond to uncertainty more thoughtfully.
This is particularly important when teaching saving and investing. These decisions involve time, trade-offs, changing information, and emotion. A combination of clear instruction, reinforcement, feedback, and hands-on learning can help make abstract ideas more understandable.
The Role of Digital Tools & Market Simulations
Financial decisions increasingly take place in digital environments. People encounter mobile banking, digital wallets, investing platforms, financial creators, online research, and AI-generated explanations. Access to these tools can make information easier to find, but it does not automatically create the ability to evaluate that information.
Digital financial literacy includes understanding how to use financial tools responsibly, assess information critically, and recognize potential risks. Learners need to distinguish educational information from personalized advice and avoid assuming that a confident explanation or popular online opinion is necessarily reliable.
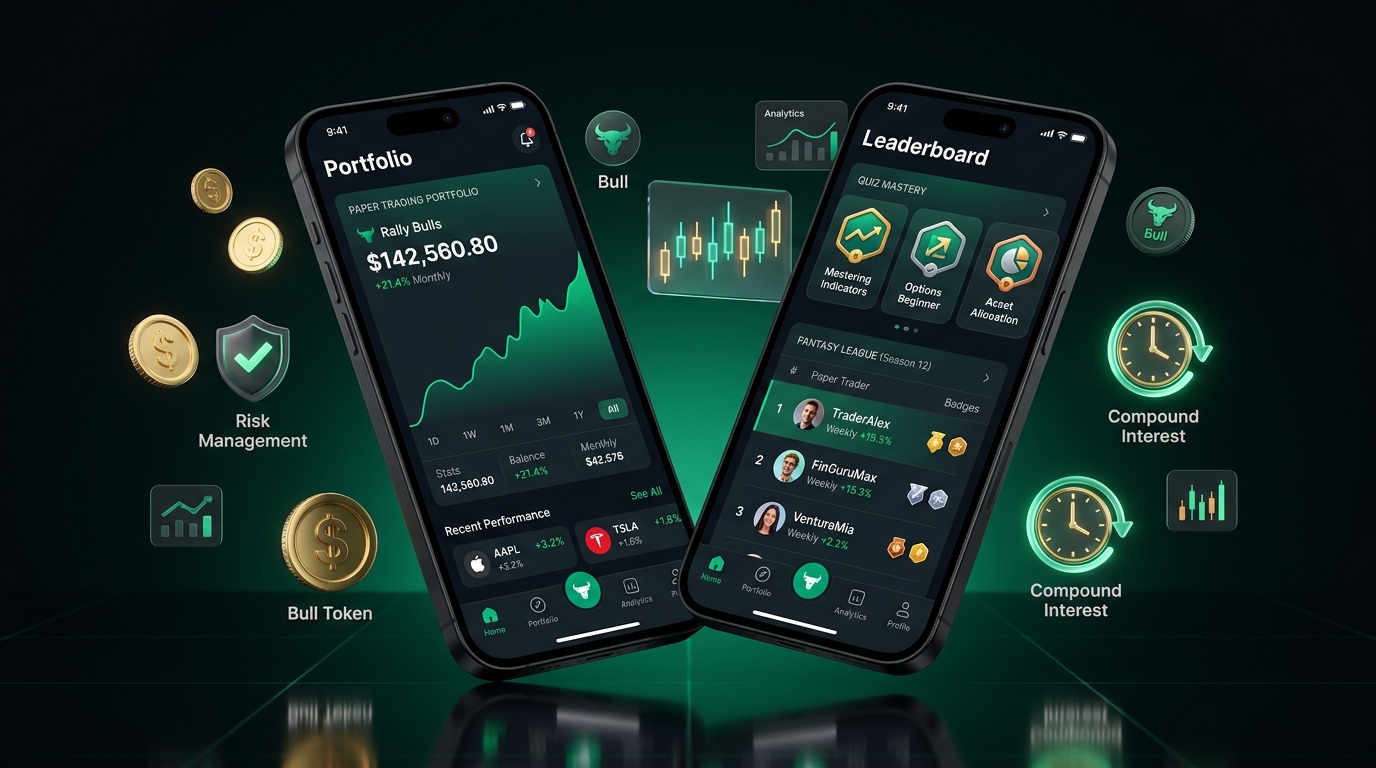
Market simulations and paper trading can offer a way to explore market movement and practice decisions without risking real capital in the simulation. Learners can observe how hypothetical portfolios change, compare approaches, and reflect on reactions to gains, losses, and uncertainty. Research tools can help them examine the information behind a market narrative rather than relying on a single signal.
Simulations have limits: they cannot reproduce every aspect of real financial decision-making, and simulated results do not guarantee future performance. Their value is educational—they provide a setting in which learners can explore concepts, test assumptions, and discuss risk before making decisions with real-world consequences.
How Rally Bulls Connects Personal Finance & Market Education
Rally Bulls brings personal finance foundations and market education into one learning environment. Its course offering covers practical topics such as spending, cash flow, paychecks and taxes, credit, debt, banking, insurance, saving, investing, goal setting, consumer protection, and entrepreneurship.
The platform also includes structured learning elements such as microlearning, quizzes, mastery thresholds, certification, and rewards. Alongside these courses, learners can explore market education through paper trading, market data, research tools, AI-supported guidance, fantasy trading leagues, and interactive practice.
Connecting these elements matters because saving and investing do not exist in isolation. Understanding a market concept is more useful when learners can relate it to goals, risk, time horizon, and broader financial circumstances. Likewise, personal finance education can be strengthened when learners have opportunities to explore how financial markets work.
Rally Bulls is designed to support learning and practice, not to promise financial outcomes or replace independent judgment. Its educational approach reflects the broader principle that financial capability grows through structured learning, repeated practice, and reflection.
Making Saving and Investing Part of Lifelong Financial Literacy
The focus on saving and investing in the 2026 National Strategy for Financial Literacy reinforces the importance of preparing people for more than immediate money management. Financial education should help learners understand how goals are built, how risk works, how money changes over time, and how financial information can be evaluated responsibly.
That preparation requires more than one lesson or a checklist of topics. Learners benefit from clear instruction, reinforcement, relevant examples, assessment, and opportunities to practice. When education connects personal finance foundations with market literacy and responsible application, it can help turn knowledge into practical capability.
Saving and investing are not simply advanced topics reserved for later in life. They are part of the financial decisions people encounter across life stages. Teaching them thoughtfully—and creating opportunities to understand them before real consequences arrive—can help make financial literacy more relevant, applied, and enduring.
Explore Financial Education with Rally Bulls
Explore Rally Bulls to learn financial concepts, build foundational knowledge, and practice market decision-making in a simulated environment. Visit RallyBulls.com to discover courses, research tools, and interactive learning experiences.
This article is for educational and informational purposes only and does not constitute financial, investment, or legal advice. It does not provide personalized investment recommendations or guarantee financial outcomes. Readers should independently verify information before making financial decisions. Market participation involves risk, including the potential loss of principal.