What Is Financial Well-Being? How Financial Literacy Can Help?
From grocery bills and rising living costs to unexpected medical expenses, managing money has become an everyday concern for many households. Even with a regular income, balancing monthly expenses, saving for the future, and preparing for financial surprises can be challenging.
The numbers reflect this pressure. According to the U.S. Federal Reserve’s 2025 household survey, 58% of American adults said rising prices had made their financial situation worse, while 59% experienced at least one major unexpected expense during the year. The survey gathered responses from nearly 13,000 adults. These U.S. findings illustrate how everyday costs and unexpected financial demands can affect household finances.
But financial security is not determined by income alone. How people manage expenses, prepare for uncertainty, and make progress toward their goals also matters. This is where financial well-being becomes important—not just in how much money people have, but in how confidently they can manage everyday expenses, prepare for unexpected challenges, and make progress toward their financial goals.
What Is Financial Well-Being?
Financial well-being is a person’s sense of financial security and freedom of choice, both now and in the future. The Consumer Financial Protection Bureau (CFPB) describes four connected elements:
- Control over day-to-day finances
- The capacity to absorb a financial shock
- Progress toward financial goals
- The freedom to make choices that allow a person to enjoy life
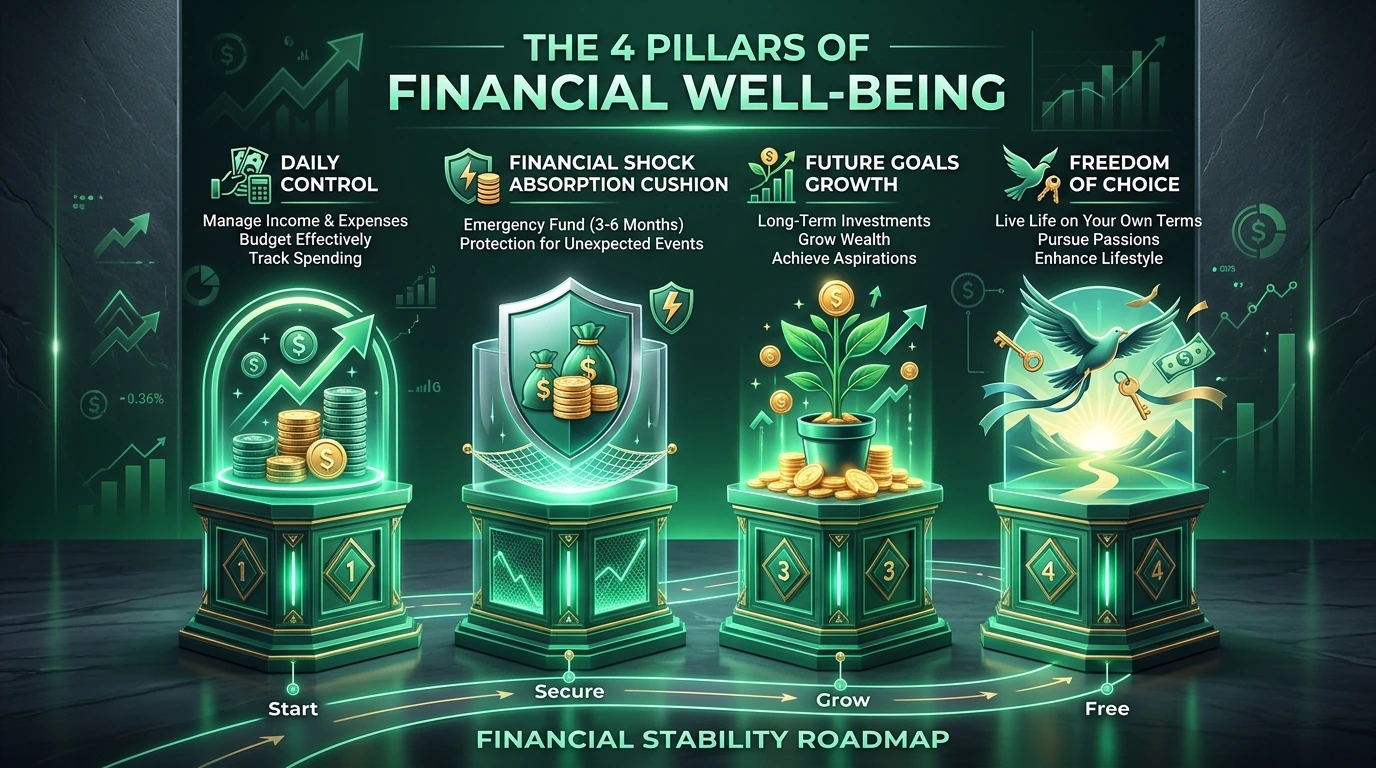
Together, these elements show that financial well-being is not measured by income, savings, or credit score alone. It also involves how prepared and in control a person feels.
An example: two people with similar incomes
Imagine two people who earn the same monthly income.
One tracks expenses, sets aside what they can for emergencies, and has a plan for paying down debt. The other has little idea where their money goes and often relies on borrowing when costs rise. An unexpected bill may be difficult for both, but the first person may have a clearer picture of their options.
This is an illustrative example, not a guarantee. Job loss, medical costs, high housing expenses, and other circumstances can affect anyone. The point is that financial well-being involves both financial conditions and the ability to manage them.
How Are Financial Well-Being and Emotional Health Connected?
Financial well-being and emotional health are related, but they are not the same. Worry about bills, debt, family responsibilities, or an uncertain future can add emotional strain. The experience differs from person to person, and financial education cannot remove every source of pressure.
A 2023 study by Yu Zhang and Swarn Chatterjee analysed data from the 2018 FINRA National Financial Capability Study in the United States. It found that financial literacy was positively associated with financial well-being, and perceived financial stress helped explain this relationship. Because the analysis was observational, it shows an association rather than proving that financial literacy alone causes better well-being.
Education can help people understand their options and plan more effectively, but it cannot replace adequate income, affordable housing, access to services, or professional mental-health support when needed.
What Is Financial Literacy, and Why Does It Matter?
Financial literacy involves the knowledge, skills, and attitudes people use to understand financial concepts and risks and make informed decisions. In everyday life, it can include planning a budget, understanding interest, comparing financial products, saving, managing credit, and recognising investment risk.
Knowledge is most useful when applied. Understanding compound interest can help people see how debt grows or savings accumulate. Comparing fees and terms can help them ask better questions before choosing a financial product. Understanding risk and diversification can support more informed investing decisions, although it cannot eliminate the possibility of loss.
A 2023 meta-analysis published in the Journal of Consumer Affairs reviewed 14 eligible articles and found positive relationships between financial knowledge, desirable financial behaviours, and financial well-being. These findings support the value of financial education, while not guaranteeing the same outcome for everyone.
How Can Financial Literacy Help Improve Financial Well-Being?
1. Build better budgeting habits
A budget helps compare income with essential expenses, debt repayments, savings, and discretionary spending. It can make recurring costs easier to see and help people plan around payment dates. If income does not cover essentials, a budget can clarify the shortfall, although it cannot solve that gap by itself.
2. Prepare for unexpected expenses
An emergency reserve can help cover costs such as urgent travel, repairs, or a temporary interruption in income. The right amount depends on personal circumstances and saving capacity. Even a small, consistent contribution may be a practical starting point.
3. Understand debt and credit
Interest rates, fees, repayment schedules, and penalties affect the total cost of borrowing. Understanding these terms can help people compare options and avoid preventable charges. Anyone already struggling with debt may benefit from reliable professional or non-profit guidance.
4. Make informed investing decisions
Investing involves uncertainty, and returns are not guaranteed. Financial literacy can help people understand risk, potential return, diversification, costs, and time horizons. It can also help them recognise unrealistic promises and pressure tactics.
5. Plan for future goals
Goals such as education, buying a home, starting a business, or retirement can give saving and spending decisions a purpose. Breaking a large goal into smaller steps can make progress easier to track and plans easier to adjust as circumstances change.
Practical Ways to Build Financial Confidence
Financial confidence grows through repeated, informed decisions—not from knowing every financial term. A few useful starting points are:
- Choose one specific goal, such as understanding monthly spending or reducing a particular debt.
- Write down income, regular expenses, debt payments, and savings to get a clearer financial picture.
- Learn one topic at a time from trustworthy educational sources.
- Compare product terms and fees before making commitments, and ask questions when something is unclear.
- Practise with examples, quizzes, or simulations before making unfamiliar decisions with real money.
- Review progress periodically and adjust plans as income, costs, and priorities change.
Financial circumstances differ. A useful plan should fit a person’s income, responsibilities, financial system, and priorities. If financial stress is affecting daily life or emotional health, consider seeking support from an appropriate qualified professional.
Build Your Financial Knowledge with Rally Bulls
Improving financial well-being starts with understanding the choices you make with money. Rally Bulls offers financial education resources designed to help learners explore personal-finance topics and strengthen their understanding of essential financial concepts.
Through structured courses and learning activities, users can learn more about budgeting, saving, investing, and other money-management topics at their own pace.
Whether you are beginning your financial education journey or looking to build on what you already know, exploring these resources can be a useful step towards making more informed financial decisions. Visit Rally Bulls to discover the available courses and continue building your financial knowledge.
Frequently Asked Questions
What is financial well-being?
Financial well-being is a state in which a person can manage current financial obligations, cope with unexpected costs, make progress toward goals, and exercise meaningful choice in their life. It includes both financial circumstances and a person’s sense of security and control.
How does financial literacy improve financial well-being?
Financial literacy can help people understand budgeting, saving, debt, credit, and investment risk. Applying that knowledge may support more informed decisions and stronger financial habits. Outcomes also depend on factors such as income, employment, costs, and access to financial services.
What is the difference between financial health and financial well-being?
The terms overlap and are sometimes used interchangeably. Financial health often describes the condition of a person’s finances and financial behaviours. Financial well-being places additional emphasis on whether a person feels secure, in control, prepared for shocks, and able to make choices.
Can financial stress affect emotional health?
Financial stress can contribute to worry and strain, particularly when people are unsure how to meet expenses or manage debt. Experiences vary, and financial education is only one possible support; it cannot resolve every financial difficulty or replace mental-health care when needed.
What are some ways to improve financial well-being?
Begin by understanding income and expenses, setting realistic goals, learning about savings and borrowing, and reviewing financial decisions regularly. Preparing for unexpected expenses when possible and seeking trustworthy guidance can also help. The most appropriate steps depend on each person’s circumstances.
Conclusion: Financial Well-Being Starts With Knowledge
Financial well-being is not simply about earning more. It is about managing everyday needs, preparing for uncertainty, working toward goals, and having greater freedom to make choices.
Financial literacy can support this process by helping people understand concepts, assess options, and build habits that fit their circumstances. Research finds relationships between financial literacy, financial behaviour, stress, and well-being, but these links are not guarantees. Income, opportunity, health, and wider economic conditions matter too. A practical first step is to choose one financial topic to learn about and apply that knowledge to a real-life goal.
This article is for educational and informational purposes only and does not constitute financial, investment, or legal advice. It does not provide personalised investment recommendations or guarantee financial outcomes. Readers should independently verify information before making financial decisions. Market participation involves risk, including the potential loss of principal.